What Does Net-Net Mean? How To Calculate Net-Net Valuations
This article on what does net net mean and how to calculate net net valuations was written by Zachary Oliva, a lawyer and investor in Houston, Texas. His investment strategy is simple: buying cheap stocks. Net net investing was Ben Graham’s strategy of choice and even helped Warren Buffett earn the best returns of his career. Get our Essential Net Net Stocks Guide to understand this strategy in detail. Click Here. Article image (Creative Commons) by Michelle TeGrootenhuis, edited by Net Net Hunter.
The term “net-net” refers to a specific type of investing. Popularized in the 1930’s by the “godfather” of value investing, Benjamin Graham, net-net investing is the process of buying a company’s common shares below a conservative estimate of the firm’s per-share liquidation value. In this article, we will review how to calculate possible values of net net stocks by paying special attention to their net current asset value. But first, what does net net mean?
Unlike net current assets, which is calculated by subtracting the current liabilities from the current assets to arrive at “net working capital”, the net- net formula subtracts total liabilities and the value of preferred shares from the current assets. The end result is an extremely conservative assessment of a company’s liquidation value. What this means for you – the investor – is a very large margin of safety should you be wrong.
What Does Net-Net Investing Mean For Investors? Potentially Big Returns.
Before committing to any investment strategy, a prudent investor should first examine the evidence. Fortunately for us, there is quite significant evidence that net-net investing will produce outsized returns. If performed rigorously and methodically, the benefits to investors could mean the difference between merely performing the same as the S&P Index, which has an average annualized return of around 10% since its inception through 2019 – to well above 20%.
For example, in a 2010 study, Jeffrey Oxman, Sunil Mohanty, and Tobias Carlisle tracked net-net performance from 1983-2008, and found that net-nets listed on American stock exchanges provided an average yearly return of 35.3%.
Another net-net study published by James Montier, a well-regarded value investor, tested baskets of global net-nets from 1985-2007, and found that net-nets trading at two-thirds of NCAV or less produced an average yearly return of 35%.
What does net net mean for consistent returns? While these returns are fantastic, one of the most important things to remember with net-net investing is that performance varies drastically from year to year. It is incorrect to assume that these outsized returns will happen each year. Instead, these returns are the average annualized returns, which means that your portfolio of net-net stocks can swing from 140% return in Year 1 to -40% return in Year 2. Investors, therefore, should expect moderate performance in most years, with a few years of outstanding Returns. Investors should also expect to underperform the market on Occasion. In the long-run, however, net-net investing is a strategy well worth your time to learn.
Often considered “The Godfather” of value investing due to his teaching and seminal writing on the subject, Benjamin Graham was also a practitioner of net-net investing. While Ben Graham’s books lack specifics, in a seminar in 1976 Graham stated:
“My first, more limited, technique confines itself to the purchase of common stocks at their working capital value, or NCAV, giving no weight to the plant and other fixed assets and deducing all liabilities in full from the current assets…I consider it a foolproof method of systematic investment once again, not on the basis of individual results but in terms of the expectable group outcome.”
Benjamin Graham’s protege and eager student at Columbia University was none other than Warren Buffett. While Buffett’s investing career and fame is mostly due to his success building Berkshire Hathaway and largely investing in large-cap companies, few investors realize that he earned his highest returns investing in what he called “cigar butt” stocks, which were net-net working capital stocks. He used this approach from 1956 until 1969, and his portfolio’s compound annual growth rate was 29.5% versus the Dow Jones at 7.4%. Why did he stop investing in net-nets? As we’ll see, net-net opportunities are mostly found in the smallest companies in the investable universe — simply put, Buffett made so much money investing in net-nets that he had to move on to large companies for investment opportunities.
Another famous investor also got his start investing in net-net stocks. Peter Cundhill, often referred to as “The Warren Buffett of Canada” completely adopted net-net investing when he learned about Benjamin Graham. Over the first ten years of his investing career, using Graham’s net-net approach Cundhill achieved a compound growth rate of 26% with no down years!
Walter Schloss was another disciple of Benjamin Graham. Schloss earned a compound annual growth rate of 16% over an incredible 40-year time span sticking to Graham’s strategy and also purchasing stocks at a low price to book ratio. While this is not a religious adherence to net-net investing, it still goes to the heart of the principle – buying stocks for less than they’re worth.
What Does Net — Net Mean? A Formula May Help
While I prefer the common sense rule that “if you buy something for less than it’s worth, it will likely be a good investment”, the operative word is “worth” and there are several ways to calculate it. To answer “What Does Net-Net Mean?” we must look at three calculations.
There are three variations of the net-net formula.
- “Quick NCAV” Net Current Asset Value = Current Assets – [Total Liabilities + Preferred Share Value]
Using the Quick NCAV approach is a quick way to assess the conservative value of a stock by calculating the net current asset value of a net net stock. You can easily access the stock’s financials using a number of different websites or the company’s annual or quarterly reports, and do some back-of-the-envelope math to determine whether the stock’s Quick NCAV warrants a deeper look at the stock. Think of Quick NCAV as a screening function.
2. “Strict NCAV” Net Current Asset Value = Current Assets – [Total Liabilities + Preferred Share Value + Off Balance Sheet Items]
Using the Strict NCAV approach, you’ll dive deeper into the net net stock by calculating the net current asset value and also looking at off balance sheet items such as pension plans, legal penalties, operating leases and others. With this approach, you’re looking at the whole company to determine whether it is a good investing opportunity.
3. “NNWC” Net-net Working Capital = [(Cash + Receivables * 75%) + (Inventory * 50%)] – [Total Liabilities + Preferred Share Value + Off
Balance Sheet Items]
Net-net Working Capital (or NNWC) was a preferred method of valuation by Benjamin Graham for a net net stock. The logic is illustrated by this quote from Charlie Munger, “The liabilities are always 100% good. It’s the assets you have to worry about.” The NNWC formula excludes the value of long term assets and discounts the value of current assets. This is a much more conservative approach to valuing a company, because you’re discounting several items.
For example, if a company has $2 Million in receivables, you might discount it by 75% on the chance that the company’s customers don’t pay or dispute the bill. Or, another example would be to discount the inventory lower than market value on the chance that the company isn’t able to sell its inventory (for example, if the inventory is very unique or customized for a specific customer) or if the market drops out of that industry and the inventory must be sold at a discount. So here, the advantages are that you could get a very, very conservative valuation on the company and demand a bigger discount, and the disadvantage is that if you are strict with this approach, it could possibly blind you to the bigger picture of putting your money to work and losing investing opportunities. Remember — stock valuation is a range, not a strict number. Be flexible.
What Does Net-net Mean For Your Portfolio?
Net-net investing is a strategy of investing in net net stocks that performs very well for small investors for a few reasons. First, there is less competition. Professional investors (mutual funds, hedge funds, and family offices) are working with large amounts of capital. By large, I mean $10M+, but in reality its generally more than $100M. What this means is that they can’t purchase stock in net-net companies that have small market caps under, say, $10M, because if they did then they would basically be taking over the company. This would go against their main business — buying stocks instead of operating businesses.
What this means for you is that there is less competition in the way of eyeballs — whether it be analysts, money managers, or the media looking at these micro and nano cap companies, so you have an opportunity to purchase them. And the smaller companies have a well-documented history of outperforming the larger companies. A 2010 study of European net-nets found a material negative relationship between firm size and returns, where the returns for the smallest net-nets came in at 16.57% versus 1.58% for the largest companies; a recent study by Ying Xiao and Glen Arnold found similar results in the UK.
Now, net-net investing works well for smaller amounts of capital, but how small? Generally, based on research by Evan Bleker, we’ve found that net- net investing works best for portfolios under $1 Million because if you were to invest that in blocks of 5% positions, you could take positions in some of the smallest publicly-traded companies, which historically perform the best. Larger portfolios up to $10 Million can still invest in net-net stocks, but it will take longer to build positions due to the low trading volume of smaller companies and you may have fewer opportunities to invest in because you may need to find larger companies than an investor with a portfolio of $1 Million or less. So, as we’ve seen, when answering the question “What Does Net Net Mean?” there are multiple avenues to address the question. Hopefully this article provided some color on strategy, returns, calculations and, ultimately, what net nets could mean for your portfolio.
To get free high-quality net net stock picks sent straight to your inbox each month, click here. Start putting together your high quality, high potential, net net stock investing strategy right now!
Net-Net
Net-net is a term used for a company with a market capitalization that is less than the difference between the company’s current assets and total liabilities. The equation does not consider long-term assets, such as property, plant, and equipment (PP&E), and intangibles.

Net-net investing is used with the underlying understanding that if the net-net (company) is sold, the current assets would be used to settle the obligations or liabilities, and the leftover amount (cash) will be worth more than the market capitalization of the company. In other words, the stock price is below the net current asset value (NCAV) of the company.
What is the Net Current Asset Value (NCAV)?
Net current asset value (NCAV) is the value of the current assets minus total liabilities, including preferred shares and off-balance sheet liabilities. NCAV is derived when you remove the long-term assets component from total assets, leaving a highly conservative estimate for a company’s value in case of liquidation. The NCAV strategy and net-net investing was founded in the 1930s by Benjamin Graham and was thought of as a good proxy to gauge a company’s real-world solvency value.
Price to NCAV of an Investment
A related concept is a multiple involving NCAV. P/NCAV can help investors and analysts determine whether a stock is under or overvalued. A low P/NCAV means the stock is undervalued. A company can alter its NCAV by buying back or issuing common shares.
Net-Net Investing: The Warren Buffet Perspective
The net-net strategy was used by Warren Buffet to grow his investments. He popularly referred to this as the “cigar-butt” investing technique. The strategy was taken from Graham, and Buffet came up with a simple rule to buy a stock. He said that if the stock price is less than 2/3 of the difference of the current assets and total liabilities, it is a net-net stock. The equation is given below:

Buffet stated that the only rule of thumb was the equation, and one does not need to analyze the company’s financial statements, conduct fundamental analysis, or make any qualitative or quantitative judgments. The strategy was a bit controversial, as most of the stocks trading as net-net stocks are not very sought after, and people avoid them as they are trading at ridiculously low prices. Moreover, people are scared to invest in companies that may undergo bankruptcy (although, there are instances of profit generation in such cases, too).
Success of Net-Net Investing Strategy
It is interesting to see that despite net-net being such a volatile strategy, the strategy yields positive returns. There are several factors as to why the net-net strategy is considered successful, including:
1. Riskiness of stocks
Looking at market data for a basket of net-net stocks, the stocks tend to show a beta (volatility) greater than 1, indicating that any movement in the markets will cause a larger impact on the change in the stock price of the stocks (indicating why such stocks might’ve historically outperformed relative to other average stocks).
2. Market liquidity
If a company’s stock is selling below its NVAC, it is normally a small company with illiquid stock. As the stock is hard to buy/sell, it will take time for the investor to react to any news that comes regarding the stock. Therefore, for such stocks, investors get a higher premium to compensate for the illiquid risk they are being exposed to.
3. Long-term reversal
A common concept in trading is that everything will eventually revert to the mean, and if anything’s previously been performing badly, it will perform well now. Studies indicate that net-net stocks performing well could be because they were not doing too well earlier (although this argument may seem flawed and biased).
4. Financial distress
Any company that is showing liquidity or solvency problems tends to garner a negative reaction from the market. The negative reaction often leads to the stock price falling way below the fair market price (making the company undervalued and, therefore, a potentially attractive investment).
Pitfalls of the Net-Net Investing Strategy
The net-net strategy comes with certain pitfalls, as not everyone can benefit from it. The investing technique does not always work, with certain investors demonstrating months of underperformance when employing the strategy. The strategy tends to do well if used for a longer time horizon (based on the success factors mentioned in the earlier section).
Another problem of the strategy arises if investors do not diversify and focus on one to two stocks to do the work. It is possible that not every net-net stock posts the gains expected, so it is very important to diversify and invest in a basket of net-net stocks. The net-net strategy works well for illiquid stocks, and as most investors are unable to purchase shares due to the thinly traded volume, they end up not benefitting from the strategy.
Related Readings
CFI offers the Commercial Banking & Credit Analyst (CBCA)™ certification program for those looking to take their careers to the next level. To keep learning and advancing your career, the following resources will be helpful:
Цены net net что это

Да нет, местный прикол. А кто сказал, что менеджмент системен у всех: в сетях, у иностранцев? Ну вот и сочиняют, порою. термины на забаву поставщикам.
Да, как обычно, ничего
Укажите, скидка включена или выключена? Т.е. со скидкой или без.
Поделиться:
Нашли ошибку? Сообщите нам!
Выделите и нажмите Ctr+Enter
Разделы
В социальных сетях
Обратная связь
Если у вас есть вопросы, задайте их через форму обратной связи
Политика конфиденциальности
Why and how to implement a net-net investment strategy world-wide
If you have found this article you have most likely heard of the net-net investment strategy developed by Benjamin Graham, the father of value investing.
Find companies below liquidation value
The idea of the strategy is to find companies trading for less than their liquidation value. This means, companies trading at such a low price that you could buy the whole company, sell off all the assets, pay off all liabilities and still make a profit.
You thus want to find companies with a market value less than its net-net working capital (this is where the name net-net investment strategy comes from).
Net-net working capital is defined as: (Cash and short-term investments + (75% of accounts receivable) + (50% of inventory) — All Liabilities)
Very conservative
As you can see the net-net formula is very conservative as it assumes the full value of inventory and accounts receivables will not be collected.
Does a net-net investment strategy work?
This sounds great you may be thinking, but does the strategy really work — over long periods of time in up and down markets?
Many independent research reports have found that a net-net strategy generates great returns: about 20-30% returns per year. A great thing for small investors like me and you is that these returns are protected from big institutional investors.
Why your net-net strategy is safe from big investors
The companies selling below their liquidation values are simply too few and are too small to make a difference in the returns of large funds so they are ignored.
Now that we know our investment strategy will be safe from Wall Street, let’s look at the results of this strategy.
Net-Net Research paper #1
This research paper proves that a net-net investment strategy works great for the small investor.
In a paper called “Ben Graham’s Net-nets: Seventy-Five Years Old and Outperforming”, three researchers tested the net-net strategy over the 24 year period from 1984 — 2008.
How they defined a net-net stock
The authors defined a net-net stocks as companies that are selling below 2/3 of Net Current Asset Value (NCAV = current assets — [liabilities + preferred stock]).
Details of the back test
The investment universe began with all stocks listed on the NYSE, AMEX, and the NASDAQ. The stocks were then filtered for deep value based on having a market price of 2/3 or less of NCAV.
The number of net-net stocks every year varied. There were only 13 stocks selling for 2/3 or less of NCAV on 1984, while there were 152 such stocks in 2002.
The equal-weighted portfolio assumed all stocks were bought on December 31 and sold after one year. Re-balancing once a year means transaction fees will not significantly impact the overall returns from the strategy.
How the strategy performed
So what were the results of this strategy?
The authors found that the average monthly return for stocks selected using this strategy was 2.55%. This is three times the 0.85% monthly return for the NYSE-AMEX Small Cap Index.
On a yearly basis, the NCAV portfolio posted an impressive 22.4% outperformance over the NYSE-AMEX index.
Here are the monthly returns for the portfolio of net-net stocks (NVAC portfolio) and the NYSE-AMEX index. The monthly returns are grouped by time period to illustrate how this strategy did over different points in time.
We see that over a total of nine time periods, there is only one time period from 1989-1991 that the net-net companies posted lower average monthly return than the market.
This is very impressive!
Reasons why this strategy posted such high returns
What explains the higher returns of stocks which are selling below their NVAC? The researchers found three reasons the strategy outperformed the market.
1. Riskiness of stocks
The relative volatility (Beta) of this basket of net-net stocks compared to the NYSE-AMEX is 1.08. A higher beta means that the stocks will exaggerate the movement of the markets.
So if the markets rise by 10%, then this basket of stocks will go up by 10.8%. Similarly, if the market falls by 10%, this portfolio of stocks will fall by 10.8%. Some research papers have found that a high beta is associated with higher levels of returns.
While this beta of 1.08 is higher than the market (NYSE-AMEX), it is not high enough to significantly explain why the net-net strategy performs really well.
2. Small Market Cap
The stocks in this net-net strategy tend to be small firms. It is well documented in financial research that smaller stocks have tended to outperform large stocks historically.
This may be to compensate for the added risk of holding small companies, since they will not be able to whether financial downturns as well as big corporations with loads of cash reserves.
3. Liquidity
The net-net stocks the authors selected were illiquid. Companies that are illiquid and difficult to trade compensate investors by providing them with higher than average returns.
High returns remained unexplained
An interesting thing is that even accounting for these 3 factors, there is still an unexplained excess return the net-net strategy generated. Even though they could not find an explanation for the excess returns, you and I can still take advantage of this spectacular strategy.
Net-Net Research paper #2
Another paper by the same authors confirms high returns of net-net strategy
The same authors came out with another research paper called “Dissecting the Returns on Deep Value Investing” that further tests Ben Graham’s net-net strategy and tries to explain why the strategy performs so well.
This time, the researchers back tested the net-net strategy over the 35 year period from 1975 — 2010, and again found that the strategy significantly outperformed the market.
How they defined a net-net stock
This time, the researchers calculated net current asset value according to the original formula put forth by Graham himself:
NCAV = [Cash + 0.75*Net Receivables + 0.5*Inventory – (Total Liabilities + Preferred Stock)]/ Shares Outstanding
Filtering the Stock Universe
The universe begins with all stocks trading on the NYSE, AMEX, or NASDAQ. The universe is filtered to select only stocks that are selling below their NCAV.
Keeping the strategy practical for me and you
To keep the strategy practical for investors like us, they removed the most illiquid stocks.
They construct two test portfolios based on two different price filters:
- One portfolio has a filter of shares that are trading for $5/share or higher. The average firm that is selling for under its NCAV and over $5 per share has a market cap of just over $40 million.
- The other portfolio has a price filter of $3 per share or higher applied to it. The mean market capitalization of firms in this portfolio is just over $30 million.
This, again, is good for us. We are able to invest in companies that are small and under the radar. In fact, 2/3 of the net-net firms had zero analysts following the company.
Holding Period
The entire portfolio of net-net stocks was created on March 1st, held for a year and sold the last day of February the following year.
What the researchers found?
The average monthly return for the portfolio with net-net stocks selling for above $5/share was 6.01%. This is over seven times the return of the S&P 500 which returned only 0.78% monthly over the same time period.
Click image to enlarge
Why does the net-net strategy do so well — possible explanations?
1. Riskiness of stocks
As in their first paper, the authors found that market risk (as measured by beta) partly explains why net-net stocks produce higher returns than the market. Since these stocks are more risky than the average stock, it must compensate by providing higher returns than the average stock.
2. Market Liquidity
The firms that are selling below their NVAC are most often small and hard to easily transact. Investors think these stocks are riskier, as if some negative news comes out of the company, it will take the investor longer to sell his shares. For this reason, illiquid stocks like the ones in this net-net strategy offer a higher return to compensate investors for the higher risk.
3. Long-term Reversal
There is some interesting research that we may talk about in another article. What this research says is that stocks that have been performing poorly in the past 3-5 years will do well in the future. Similarly, stocks that have been doing well in the past 3-5 years will perform poorly in the future.
In order to become as cheap as they are now, net-net stocks must have been performing poorly in the past 3-5 years. The authors of this research paper found that this ‘long-term reversal’ factor may have contributed to the good returns of the net-net strategy.
4. Financial Distress
Financial Distress is a measure of how difficult it will be for a company to repay all their liabilities. The researchers found that companies with declining earnings were thought to be more distressed than peer firms. The market overreacted to recent poor performance and under-price these stocks.
What makes one net-net stock better than another?
1. Low Analyst Coverage
The paper found a positive association between less analyst coverage and higher returns. Without the analyst report, it may be that investors have a harder time finding these net-net companies. You and I have no trouble finding these companies with a stock screener.
2. Low trading volume
Stocks with low trading volume generate higher returns than stocks with a higher trading volume. This is partly because of the higher returns due to low liquidity discussed earlier. It is also because institutional investors have a much harder time taking a big position in the company.
Net-Net Research paper #3
Does the net-net strategy also work outside the U.S.A?
We have seen research that shows the outperformance of this strategy in the United States, but can international investors also take advantage of the strategy?
Two researchers in the United Kingdom set out to find out if the net-net strategy also works outside the United States in a research paper called “Testing Benjamin Graham’s Net Current Asset Value Strategy in London”
What was the back test period and investment universe?
The researchers populate their investment universe with all stocks that have traded on the London Stock Exchange over the 24 years from 1981 — 2005.
They then filter out companies with more than one type of ordinary share class. So if a firm had class A and class B shares, it would not be included in the study.
Further, firms incorporated in countries outside of the UK were excluded from the study. Financial sector companies were also eliminated from the stock universe. The reason why is not explicitly given by the authors but most likely because the net-net calculation cannot be applied to banks.
Making the results more accurate — avoiding biases
Survivorship bias was eliminated by including companies that have been delisted from the exchange.
What the authors classified as a net-net stock
The authors take the NCAV of a firm and divide it by the total market value (MV) of the stock. Companies with a NCAV/MV ratio higher than 1.5 were counted as net-net stocks.
This means if the company were to go bankrupt and liquidate all its current assets, they would sell for more than 50% of the company’s current market value.
How often did the researchers rebalance the portfolio?
The portfolio was formed annually in July, and used accounting data made public in December to calculate NCAV. So no look ahead bias here!
On average, there were 1109 firms to select from when the portfolios were formed in July.
Ok, so how did the strategy perform in a market outside of the United States?
Performance of net-net stocks in the UK
The average raw annualized return of an equal weighted portfolio of net-net firms was 31.19%. This is compared to only 20.51% average raw returns for the market index.
Notice that this difference of 10.68% a year adds up to a very big difference even after just 5 years. Cumulative returns after 5 years are almost double for the net-net strategy than just investing in the market.
High Returns puzzle researchers again
The authors try to explain the high returns for the net-net strategy using similar factors to the papers we discussed earlier. Like the other researchers, they could not fully explain the high returns of the net-net strategy.
Net-Net Research paper #4
Variations to the net-net strategy
Researchers from the U.S. and South Korea attempt to see if they can modify the net-net strategy and extract higher returns in this research paper Testing Benjamin Graham’s net current asset value model.
Their back test period was the 13 years from 1999-2012. This is a shorter back test time that other papers, but it can still help us gain some insights in how to best modify the net-net strategy.
Here is what they did to determine the best variations of the net-net strategy.
- Cheaper stocks (Higher NCAV/Market Value of company) leads to higher returns
- Different holding periods lead to different returns
- Only holding net-net stocks during growth periods leads to higher returns
It is logical to think that the higher a firm’s’ NVAC is relative to its market value, the higher its returns will be. To test this hypothesis out, the authors break up net-net stocks into 3 different categories:
- Portfolio 1 = NCAV/MV > market price×1
- Portfolio 2 = NCAV/MV > market price×2
- Portfolio 3 = NCAV/MV > market price×5
So, for example, the number 3 portfolio only includes companies where if all the assets of the company were to be sold, the money received would be more than 5x the market cap of the company.
How did these three different portfolios perform?
Like expected, investing in net-net stocks with higher NCAV/MV generated higher returns. However, these stocks also performed worse in down markets. The authors found that holding periods of 4 weeks and 1 year had the highest returns.
They added a market timing factor
However, there is one big change that the authors tested.
The authors used an indicator to purchase net-net stocks only when market conditions were favourable. I recommend reading the actual paper to get a full explanation of this indicator, but I will try to give you a simple explanation.
Basically, markets are said to be undervalued when the forward earnings yield (inverse of the Price to Earnings ratio) of the S&P 500 is higher than the long term treasury yield. Why this is the case is beyond the scope of this article, but I encourage you to read the paper and do your own research if you are interested.
The strategy of buying net-net stocks only when the forward earnings yield of the S&P 500 is higher than the long term treasury yield is called “hedging” by the authors.
The returns produced when using this hedging strategy were very different than before.
The authors found that 1 year was the best holding period when only investing during favourable market conditions. In fact, as the holding period got shorter, the returns got worse.
A portfolio of stocks with NVAC at least 1x greater than current market value of the firm produced 16.84% returns annually if the hedging strategy described above was used. If the stocks were only held for 4 weeks, the net-net strategy returned -3.28%.
A portfolio of stocks with NVAC at least 2x greater than current market value of the firm produced 17.48% returns annually if the hedging strategy described above was used. If the stocks were only held for 4 weeks, the net-net strategy returned -3.11%.
A portfolio of stocks with NVAC at least 5x greater than current market value of the firm produced 19.37% returns annually if the hedging strategy described above was used. If the stocks were only held for 4 weeks, the net-net strategy returned -1.31%.
Key Things to remember about a net-net strategy
- Returns are safe from big institutional investors
- Strategy has shown to produce 20 — 30% annual returns
- Create a margin of safety by investing in only stocks with NVAC 1.5x above market cap of the firm
- Re-balance yearly or less to keep transaction costs incl. bid ask spreads low
- The strategy invest in under the radar net-net firms without any analyst coverage
- If possible, invest in net-net stocks when forward earnings yield of S&P 500 is higher than long term bond yield
- Net-net strategy also works outside of the United States
You must buy a basket
As you can imagine there is a good reason why companies get this undervalued. If you look at the list of net-net ideas a screen comes up with you will see that these are companies that have problems – most likely BIG problems.
This is why Benjamin Graham suggested that you lower your risk by investing in a number of net-net investments, he suggested that you invest in basket of 30 such ideas to lower the risk of any one company (or a few) going bankrupt.
The idea is that other companies in the basket will do so well, more than compensating for the few companies that may go bankrupt.
How to find your own Net-Net ideas
Net Current Assets Value (NCAV) = (Current assets (cash, inventories and accounts receivable) – All possible Liabilities) / Market value
With all possible liabilities calculated as (Total Assets — Common Shareholders Equity)
Margin of safety
As you can see in the above ratio calculation nothing is done to lower the value of inventory or accounts receivable as Benjamin Graham suggested.
NCAV > 1.5
To make up for this you can make sure that the companies the stock screen have a net current asset value ratio of more than 1.5.
This means that all the companies have net assets (after all liabilities have been deducted) worth at least 1.5 the current market value of the company.
Step by step instructions
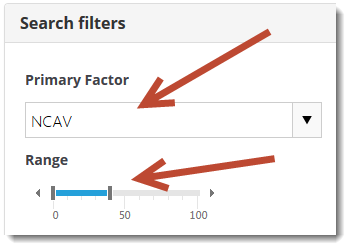
Step 1 – Use NCAV in the Primary slider
Select the cheapest companies in terms of NCAV
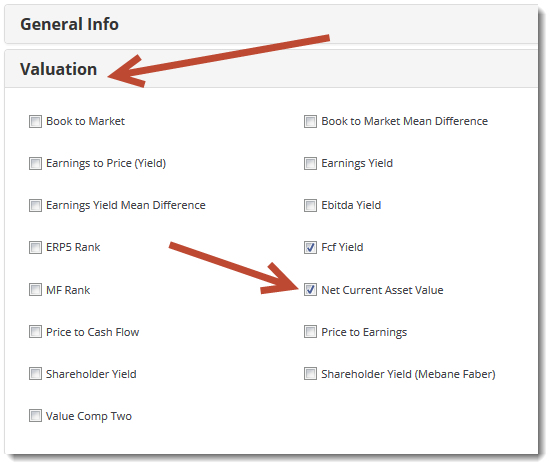
Step 2 – Add Net Current Asset Value as an output column
Click the Choose Columns button, click on the valuation tab and tick the box next to Net Current Asset Value.
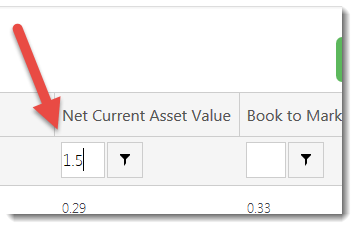
Step 3 – Filter for companies with a Net Current Asset Value of greater than 1.5
To do this type 1.5 into the box below the Net Current Asset Value column.
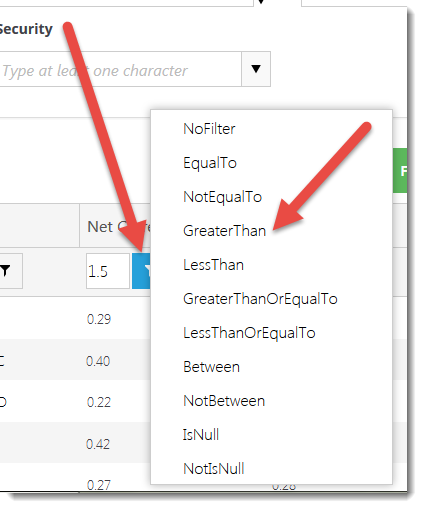
Next click on the small funnel icon and select GreaterThan
First 10 net-net investment ideas
Below is a list of 10 net-net ideas sorted (click on the column heading to sort) by net current asset value (NCAV):
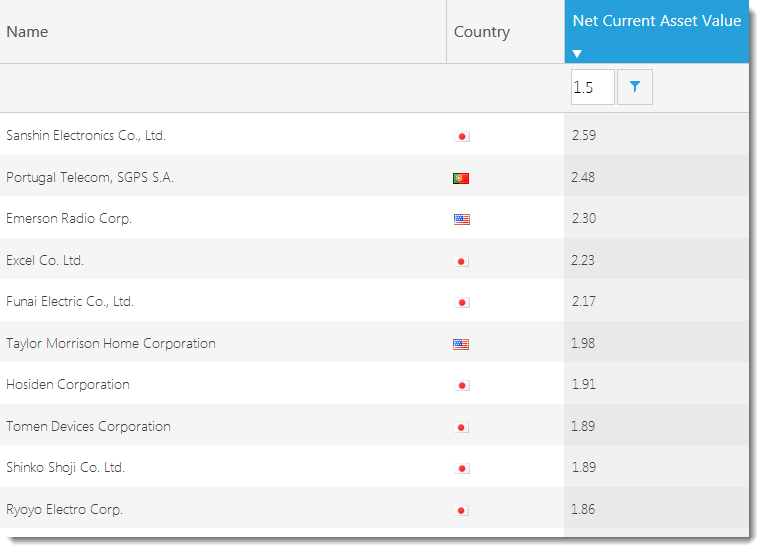
Click image to enlarge
How to select quality Net-nets
As I mentioned a net-net company is usually a low quality business. You can however improve the quality of your net-net ideas by using the Piotroski F-Score. You can find more information on the Piotroski F-Score here: This academic can help you make better investment decisions – Piotroski F-Score
If you use the above list but remove all companies with a Piotroski F-Score of less than 5 (Piotroski F-Score values go from 0 to 9) the list of investment ideas look like this:
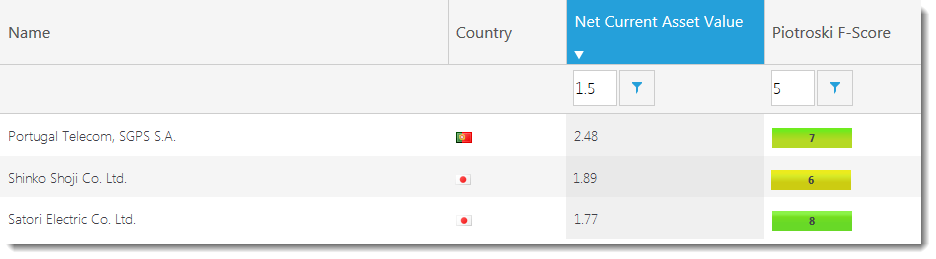
Click image to enlarge
Net-net with positive free cash flow
If you want to screen out companies that are burning cash (this decreased NCAV over time) you can do this by selecting net-nets with a cash flow to capital expenditure ratio greater than 1. (Cash flow to Capex = Cash from Operations / Capex)
This will make sure the company has been able to meet all its capital expenditure with cash flow generated by the business, or you can say the company has positive free cash flow.
Your research is required
Please remember, as with all screens, the names the screener comes up with should just be the start of your research process. And because net-nets are high risk investments detailed research of the company’s financial statements is very important.
Wishing you profitable investing
PS To get all the tools you need to implement this strategy in your portfolio sign up here.
PPS It’s so easy to put things off, why not sign up right now?