Continuous Contracts Explained
Let’s begin with a futures market — Soybean Oil, or Soyoil for short — and say that there is no such thing as a continuous series of Soyoil futures prices. Futures markets are comprised of individual contracts, each with a pre-determined life-span. At any stage, the market consists of a number of contracts, or "delivery months", that have expiry dates stretching out into the future. As one contract expires, another is listed for trading, and so the cycle continues. The only way that a long-term continuous history of Soyoil prices can be examined is to access a record of cash market prices.
Of course, it’s always possible to "splice" the individual Soyoil futures contracts together in some way, so as to represent their history. But it must be borne in mind that the result will merely be a representation of that history, or a computation, that is handled by a particular algorithm.
Splicing contracts together
If all delivery months in the Soyoil cycle were "equal", it would make sense to splice them together by a very simple algorithm: "when one contract expires, begin to display the next". This type of series is called a "spot-month continuous". But delivery months, particularly in commodity futures markets, are generally not equal. The delivery months that the Chicago Board of Trade offers for Soyoil trading are intended to cover the underlying agricultural cycle so as to give industry participants full scope to hedge their specific needs. They are not spread equally through the calendar year. For instance, there is a sequence of contracts expiring in July, August, September and October and then a jump to December.
A hedger may not be interested in the August, September and October contracts at all, and may prefer to trade in the December contract well before any of the intervening contracts have expired. Trading volume tends to be spread unequally between different delivery months. Sometimes an exchange introduces a new delivery month into a market cycle and the industry completely ignores it.
The same disinterest may be shown by a speculator. He may have his own reasons for trading December Soyoil "early" in the cycle. For instance, he may be discouraged by the necessity of "rolling" through all of the intervening contracts, incurring commission costs and potential "slippage" each time. If the trading volume is sufficient to allow it, why not just jump straight into December?
The "spot-month" continuous contract — how useful is it?
It is often assumed that a continuous contract has to display the "spot month" at all times in order to be "correct". This is not the case. A continuous contract is a representation and that representation is correct only in so far as it is useful. There is no single "correct" way to compute a continuous contract for any futures market. The "spot month" representation is probably the most popular, but not necessarily the most useful.
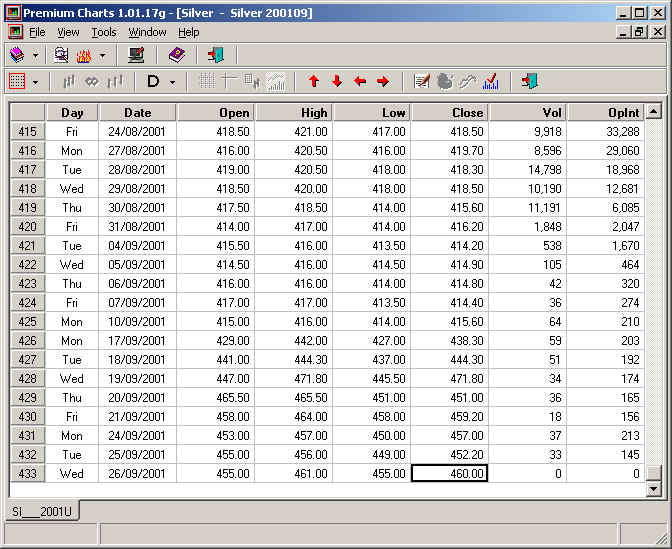
To understand why, let’s consider Silver. An examination of the trading volumes in Silver futures reveals a marked decline from about a month before the expiry of each delivery month (see table below). This decline coincides with First Notice Day. If a trader remains in a contract after First Notice Day, he is at risk of having to take delivery of the underlying commodity.
A Silver contract still has a month to run after First Notice Day, but very soon only a handful of industry participants will be trading it. Is there any use in incorporating the last month of Silver prices into a continuous contract if that portion of the delivery month will never be traded? There might be, if no other prices were available, but current prices are always available from any of the subsequent delivery months.
It might be argued that the spot month prices are the most important from an "overall analysis point of view". This argument amounts to saying the following: "My next trade will be in October Cotton. But I shan’t look at prices from the October contract, even though I am able to. I shall continue to study July prices, because July is the spot month, and it still has a fortnight to run." This argument becomes especially curious when it is considered that the July and October Cotton contracts virtually cover different crops!
Rolling on Volume and/or Open Interest
Another simple algorithm for constructing continuous contracts is to follow the market’s lead. When volume and/or open interest become larger in a back-month, the series leaves the current contract and moves to the back-month. On the face of it, this is a clever algorithm, as it automatically circumvents liquidity problems. It may also surmount the Notice Day problem, by assuming that trading volume always leaves the current contract in time.
The trouble with the algorithm is its over-riding assumption — that liquidity is the only appropriate criterion for selecting delivery months. Let’s consider the Eurodollar contract, which is one of the most heavily traded in the world. There is reasonable volume in at least the first 12 listed quarterly contracts. Furthermore, there will often be little difference between the nearby quarterly contract and the next one out in terms of volume — the volume and open interest will be huge in each.
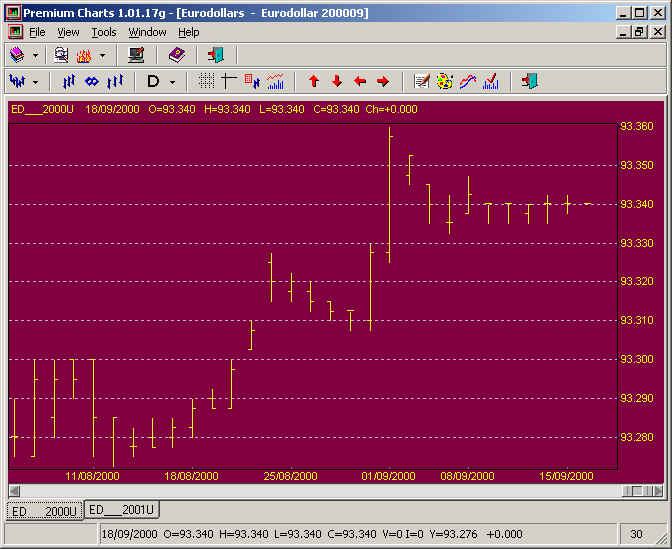
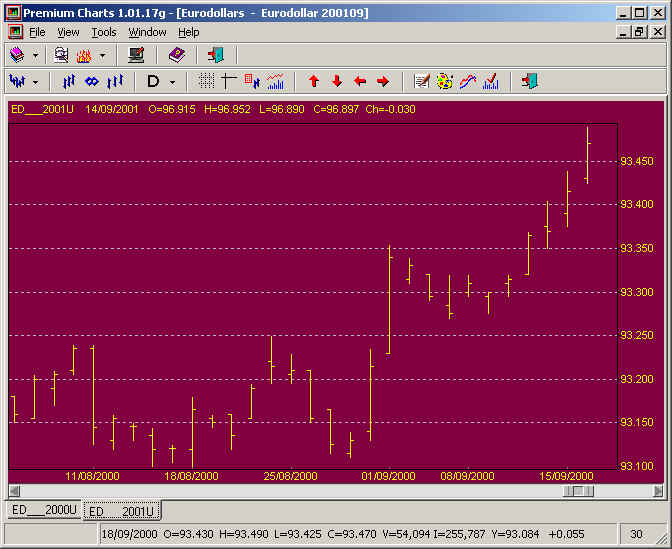
This invites an obvious question: if the contract with the greatest volume is the "correct" one to be following, why is there so much interest in the others? The answer is that different delivery months offer different trading opportunities, both for hedgers and speculators. The Eurodollar futures market attempts to predict the level of interest rates on Eurodollar deposits at specific times into the future. The closer that the time is to "now", the more sensitive the market is to what happens to cash rates. Because of this, prices in different delivery months can move in contrasting manner. For instance, prices in the spot month may move quite sharply while back months remain relatively calm, and vice versa (see charts below). It is even possible for prices in one month to go up and in another down, although this sort of divergence is most common in commodity futures markets, where seasonal factors play a larger role.
The assumption that all delivery months are homogenous, which is implicit in the volume/open interest algorithm, is mistaken, at least for most types of futures markets. This is easily demonstrated if different roll schedules are used to construct continuous contracts for the same market. The variation in the results is often quite apparent to the naked eye.
Some system traders are happy for their continuous data to be "handed" to them by an algorithm such as rolling on volume/open interest. Others prefer to construct their own data and experiment with the results. Rolling on volume and/or open interest is a good way to construct continuous contracts, as long as the question of which delivery month appears in the series at any time is not considered an issue.
Part 2 of the article looks into a problem with simple "spliced" contracts and introduces "back-adjusted" contracts.
Illustrations
1) The first chart below show the September 2000 Eurodollar contract trading through a 9-point range in the final 30 days of its life.
2) At the same time, the September 2001 Eurodollar contract was trading through a 39-point range.
3) The table shows volume and open interest in the September 2001 Silver contract falling away rapidly towards expiry.
Part 2 of the article looks into a problem with simple "spliced" contracts and introduces "back-adjusted" contracts.
futures contract
futures contract — A legally binding agreement, made on the trading floor of a futures exchange, to buy or sell a commodity or financial instrument sometime in the future. Futures contracts are standardized according to the quality, quantity, and delivery time and… … Financial and business terms
Futures contract — Agreement to buy or sell a set number of shares of a specific stock in a designated future month at a price agreed upon by the buyer and seller. The contracts themselves are often traded on the futures market. A futures contract differs from an… … Financial and business terms
Futures Contract — A contractual agreement, generally made on the trading floor of a futures exchange, to buy or sell a particular commodity or financial instrument at a pre determined price in the future. Futures contracts detail the quality and quantity of the… … Investment dictionary
futures contract — An agreement to buy or sell a fixed quantity of a particular commodity, currency, or security for delivery at a fixed date in the future at a fixed price. Unlike an option, a futures contract involves a definite purchase or sale and not an option … Accounting dictionary
futures contract — A present right to receive at a future date a specific quantity of a given commodity for a fixed price. Clayton Brokerage Co. of St. Louis, Inc. v. Mouer, Tex.Civ.App., 520 S.W.2d 802, 804. Commodity futures contracts?? are commitments to buy or… … Black’s law dictionary
futures contract — A present right to receive at a future date a specific quantity of a given commodity for a fixed price. Clayton Brokerage Co. of St. Louis, Inc. v. Mouer, Tex.Civ.App., 520 S.W.2d 802, 804. Commodity futures contracts?? are commitments to buy or… … Black’s law dictionary
futures contract — An agreement to buy or sell a fixed quantity of a particular commodity, currency, or security for delivery at a fixed date in the future at a fixed price. Unlike an option, a futures contract involves a definite purchase or sale and not an option … Big dictionary of business and management
futures contract — / fju:tʃəz ˌkɒntrækt/ noun a contract for the purchase of commodities for delivery at a date in the future COMMENT: A futures contract is a contract to purchase; if investors are bullish, they will buy a contract, but if they feel the market will … Dictionary of banking and finance
futures contract — A *contract to buy or sell a denned quantity of a *commodity *currency, or *security at a specified date at a specified *price. Unlike an *option, a futures contract involves a firm commitment to buy or sell in accordance with the terms of the… … Auditor’s dictionary
Current contract in front что это
Reddit and its partners use cookies and similar technologies to provide you with a better experience.
By accepting all cookies, you agree to our use of cookies to deliver and maintain our services and site, improve the quality of Reddit, personalize Reddit content and advertising, and measure the effectiveness of advertising.
By rejecting non-essential cookies, Reddit may still use certain cookies to ensure the proper functionality of our platform.
For more information, please see our Cookie Notice and our Privacy Policy .
Get the Reddit app
r/FuturesTrading is a place to discuss futures, commodities, etc. Share futures trading insight, tips, and your trades!
For example, HO1! (continuous front month Heating oil) is different to HOM2022 when comparing just this month's portion.
What Is Front Month? Definition, How It Works, and Example
Thomas J Catalano is a CFP and Registered Investment Adviser with the state of South Carolina, where he launched his own financial advisory firm in 2018. Thomas' experience gives him expertise in a variety of areas including investments, retirement, insurance, and financial planning.
Skylar Clarine is a fact-checker and expert in personal finance with a range of experience including veterinary technology and film studies.
What Is Front Month?
The term «front month» refers to the nearest expiration date in futures trading. It is commonly used when describing futures or options contracts with earlier expiration dates. Put simply, it is the shortest length of time for which the contract can be purchased. Contracts that fall into this category tend to be very heavily traded and are often very liquid because of the short expiry date. A front month is the opposite of a back month, which denotes expiration dates for contracts that are far off in the future.
Key Takeaways
- A front month is the nearest expiration date for a futures or options contract.
- The front month represents the shortest length of time for which the contract can be purchased
- Front months are typically the most heavily traded and most liquid options and futures contracts.
- The spread between the underlying security's front month futures price and its spot price will usually narrow until converging at expiration.
- The opposite of a front month is the back month, which refers to a date further off in the future.
Understanding Front Month
Derivatives are financial contracts whose value is based on the price of an underlying asset. Both options and futures are two types of contracts. An options contract gives the investor the right but not the obligation to buy or sell the underlying asset at a specific price by a certain date. A futures contract, on the other hand, obligates the holder to buy or sell the asset on a specific date in the future.
A contract’s expiration date refers to the time at which it matures. In some cases, contracts expire far off in the future. In other instances, they expire within a relatively shorter period of time. The expiration month in these latter contracts is called a front month.
These contracts tend to be the most heavily traded and the most liquid options and futures contracts for a given series or issue. Although it’s not always the case, the listed front month is typically in the same calendar month. Front-month prices are normally the ones used when quoting that security’s futures price.
The spread between the underlying security’s front month futures price and its spot price is normally the narrowest and continues to shrink until they converge at expiration. The use of front-month contracts requires an increased level of care since the delivery date may lapse shortly after purchase. That’s because it requires the buyer or seller to actually receive or deliver the contracted commodity.
The front month is also sometimes referred to as the near month or the spot month.
Special Considerations
Futures contracts have different expiration months throughout the year and many extend into the next year. Each futures market has its own specific expiration sequence. For example:
- Financial instruments, such as Standard & Poor’s (S&P) 500 E-mini futures or U.S. Treasury bond futures, use the quarterly expiration months of March, June, September, and December (contract month coded — H, M, U, and Z).
- Commodities markets are loosely tied to their mining, harvest, or planting cycles, and may have five or more delivery months in one year. Energy futures, such as crude oil, have monthly expiration dates as far into the future as ten years.
It is important to note that expiration dates and the last day of trading dates are not the same. For energy especially, contracts stop trading in the month prior to the expiration month. Therefore, selecting the proper expiration month for a trading strategy is quite important.
Backwardation and Contango
Backwardation and contango are terms that describe the shape of a commodity futures curve.
Backwardation occurs when a commodity’s futures price is lower for each successive month along the curve, resulting in an inverted futures curve. The futures spot price, which is the front month price, will be higher than the next month’s price and so on. This is usually the result of some disruption to the current supply of that commodity. In other words, backwardation is when a commodity’s current price is higher than its expected future price.
Contango refers to a normal futures curve for a commodity where its futures price is higher for each successive month along the curve. The spot price is lower than the next month’s price and so on. This makes sense intuitively given that physical commodities will incur costs for storage, financing, and insurance. The longer out until expiration, the higher the costs. Simply put, contango is when a commodity’s futures price is expected to be more expensive than the spot price.
Both states of the market are important to know for futures trading strategies that involve rolling over positions as they near their respective expiration dates.
Front Month vs. Back Month
As noted above, contracts with front month expiration dates are those that come due in the shortest amount of time possible. These contracts are often paired with back-month contracts to create calendar spreads.
Back-month contracts have later expiration dates than front-month contracts and are also called far-month contracts. Unlike front-month contracts, prices for contracts that expire in back months have different prices. As such, they tend to be more expensive. That’s because there is a lot more uncertainty associated with these contracts.
Back-month contracts are also less liquid than those with front-month expiration dates. Because of this, there is a lot less trading volume, which can add to the overall risk
Example of Front Month
Here’s a hypothetical example to show demonstrate how a front-month contract works. Let’s say a day trader in crude oil futures purchases a futures contract and agrees to purchase 1,000 barrels of oil for $62 per barrel with the front month being July. This means the contract expires in July and there is no earlier contract available.
If the trader still holds the contract at its expiration, they will need to take possession of 1,000 barrels of crude oil. The trader will take advantage of market volatility in the days leading up to the expiry date and attempt to make a profit on their right to the barrels of oil before the contract expires.